Types of Currency: From Ancient Tokens to Modern Money
Currency has evolved dramatically throughout human history, reflecting changes in society, technology, and economic systems. From tangible commodities to digital representations of value, different forms of money have played crucial roles in trade, commerce, and financial development. Understanding these types helps illuminate how economies function and how value is preserved and exchanged across cultures and eras.
Traditional Paper Money
Government-issued banknotes that serve as legal tender in modern economies.
Advantages
- Widely accepted for everyday transactions
- Backed by national governments and central banks
- Portable and easy to use
- Recognizable through security features and designs
Limitations
- Subject to inflation and devaluation
- Vulnerable to counterfeiting
- Requires physical handling and storage
Best for: Daily purchases, cash-based economies, international travel
Commodity Money
Items with intrinsic value used directly as a medium of exchange.
Advantages
- Has inherent worth (e.g., gold, silver)
- Universally trusted due to tangible value
- Resistant to inflation in stable supply conditions
- Historically foundational to monetary systems
Limitations
- Difficult to transport in large quantities
- Value can fluctuate based on market demand
- Lacks divisibility and uniformity in raw form
Best for: Barter systems, historical trade, wealth preservation
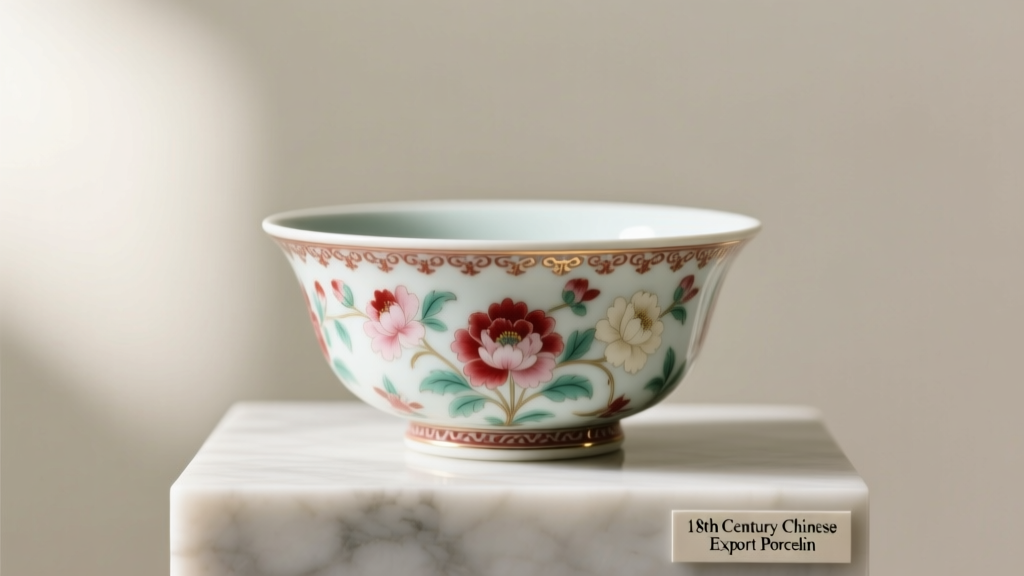
Ceramic Money
Early forms of currency made from fired clay or ceramic materials.
Advantages
- Durable and resistant to wear
- Easy to mold and mark with denominations
- Used in early standardized trade systems
- Archaeologically significant
Limitations
- Brittle and prone to breakage
- No intrinsic metallic value
- Not used in modern economies
Best for: Historical study, ancient trade systems (e.g., early China)
Representative Money
Paper or token currency that represents a claim on a physical commodity like gold or silver.
Advantages
- Easier to carry than bulk commodities
- Redeemable for tangible assets
- Helped transition from barter to abstract money
- Foundation for modern banking systems
Limitations
- Dependent on trust in issuing authority
- Risk of default if reserves are insufficient
- Largely obsolete since the end of the gold standard
Best for: Pre-fiat economies, historical financial systems, monetary education
Islamic Money
Currency and financial instruments compliant with Shariah law principles.
Advantages
- Prohibits interest (riba), promoting ethical finance
- Built on real assets and risk-sharing models
- Encourages social equity and charitable giving (zakat)
- Growing global relevance in ethical investing
Limitations
- Complex compliance requirements
- Limited availability outside Muslim-majority regions
- Slower adoption in conventional banking environments
Best for: Shariah-compliant finance, ethical investment, Muslim-majority economies
| Type | Intrinsic Value | Modern Use | Key Feature | Historical Significance |
|---|---|---|---|---|
| Traditional Paper Money | No | Widespread | Legal tender, government-backed | Modern standard for daily transactions |
| Commodity Money | Yes | Limited | Value in material (gold, shells) | Foundation of early trade systems |
| Ceramic Money | No | None | Durable, engraved tokens | Early standardization in ancient China |
| Representative Money | Indirect | Historical | Redeemable for gold/silver | Bridged commodity and fiat systems |
| Islamic Money | Varies | Specialized | Shariah-compliant, interest-free | Ethical finance with growing influence |
Expert Insight: While traditional paper money dominates daily life, understanding alternative forms like commodity and Islamic money provides valuable context for global economics, investment strategies, and cultural approaches to wealth and exchange.
Design of Currency: Security, Symbolism, and Functionality
The design of modern currency is a sophisticated blend of art, technology, and economic strategy. Far beyond mere visual appeal, currency serves as a national symbol, a tool for commerce, and a frontline defense against counterfeiting. Governments and central banks invest heavily in designing banknotes that are secure, durable, and representative of national identity. This guide explores the key elements that shape the design of currency today, from advanced anti-counterfeiting measures to cultural symbolism and practical usability.
Security Features: Protecting Against Counterfeiting
One of the most critical aspects of currency design is ensuring authenticity. With the rise of digital printing and scanning technologies, counterfeiters have become increasingly sophisticated, prompting central banks to integrate advanced security features into every banknote. These include:
These features not only deter fraud but also empower the public to verify authenticity quickly. As technology evolves, so too does the "arms race" between currency designers and counterfeiters, leading to continuous innovation in security design.
Symbolism and National Identity
Currency is more than a medium of exchange—it is a storytelling medium. The imagery and symbols featured on banknotes reflect a nation’s history, values, and cultural pride. Carefully curated designs often include:
Historical Figures
Leaders, revolutionaries, scientists, and artists are commonly depicted to honor their contributions. For example, the U.S. $1 bill features George Washington, while India’s ₹2000 note honors Mahatma Gandhi. These portraits serve both educational and symbolic purposes, reinforcing national identity.
National Landmarks and Nature
Iconic structures like the Eiffel Tower (France), the Great Wall (China), or natural wonders such as mountains and rivers are used to celebrate geographical heritage and foster unity among citizens.
Even the colors and motifs carry meaning—blue may represent stability, green for prosperity, and gold for wealth. The selection process involves extensive consultation with historians, artists, and government bodies to ensure cultural sensitivity and broad public acceptance.
Denomination Structure and Practical Use
A well-designed currency system includes a logical range of denominations to support smooth economic transactions. From low-value coins to high-denomination notes, each plays a specific role:
| Denomination | Typical Use Case | Design Differentiation |
|---|---|---|
| 1–10 Units | Small purchases (snacks, transit) | Smaller size, distinct color, simplified design |
| 20–100 Units | Everyday spending (groceries, bills) | Standard size, enhanced security features |
| 200+ Units | Large transactions, savings | Larger size or unique color, highest security level |
Clear visual distinctions—such as color coding, size variation, and layout hierarchy—help users quickly identify values, reducing errors in fast-paced environments like retail or banking.
Materials and Long-Term Durability
The material used in currency production significantly impacts its lifespan and environmental footprint. Traditionally, cotton-based paper was standard, but many countries have transitioned to polymer substrates due to their superior durability:
Paper Currency
Made from cotton and linen fibers, traditional paper notes are biodegradable but prone to tearing, moisture damage, and wear. They typically last 12–18 months in circulation.
Polymer Currency
Plastic-based notes are water-resistant, harder to tear, and can incorporate transparent windows and embedded security elements. They last 2–4 times longer than paper, reducing production costs and environmental impact over time.
Countries like Australia, Canada, and the United Kingdom have successfully adopted polymer notes, citing improved hygiene, longevity, and security as key benefits.
Ergonomic and User-Centered Design
Effective currency must be easy to handle, store, and use in both human and machine contexts. Ergonomic considerations include:
These features ensure that currency remains accessible and efficient for all users, supporting financial inclusion and seamless daily transactions.
Note: While digital payment methods are rising, physical currency remains vital for financial resilience, privacy, and accessibility. Its design continues to evolve in response to technological, economic, and social changes. Central banks must balance innovation with familiarity to maintain public trust and ease of use.
Scenarios of Currency: Real-World Applications in Modern Finance
Currency is far more than just paper notes and coins—it plays a central role in nearly every financial interaction in today's globalized economy. From everyday purchases to international investments, understanding how currency functions across different scenarios empowers individuals and businesses to make informed, strategic decisions. Below are five key areas where currency dynamics significantly influence outcomes, with practical insights and expert recommendations.
Daily Transactions
Whether purchasing a morning coffee, filling up at the gas station, or paying monthly rent, local currency facilitates essential day-to-day transactions. The value of money—often influenced by inflation, interest rates, and economic stability—directly impacts purchasing power and consumer confidence.
- Cash-based economies rely heavily on stable currency values to maintain trust in everyday commerce
- Digital wallets and contactless payments have increased the speed and convenience of transactions, but still depend on accurate currency conversion and real-time exchange rates
- Price transparency and fair valuation are critical in preventing hidden costs due to fluctuating currency values
Key insight: Even in digital-first societies, understanding local currency trends helps consumers budget effectively and avoid overspending.
Travel and Foreign Exchange
Traveling abroad introduces the practical importance of currency exchange. The amount of local currency you receive for your home currency can significantly affect your travel budget, from dining out to booking accommodations.
- Exchange rates at airports are often less favorable due to convenience premiums—planning ahead can save 5–10% on conversion costs
- Using no-foreign-transaction-fee credit cards can offer better exchange rates than cash exchanges
- Dynamic currency conversion (DCC) at ATMs or point-of-sale terminals may seem convenient but often includes hidden markups
Pro tip: Monitor exchange rate trends before your trip and use apps that provide real-time rate comparisons to maximize your travel budget.
Investment Strategies
Global investing requires a deep understanding of currency movements, as exchange rate fluctuations can amplify or erode investment returns—even when the underlying asset performs well.
- A strengthening home currency can reduce the value of foreign stock or bond returns when converted back
- Investors in international real estate must account for both property appreciation and currency volatility
- Hedging strategies, such as currency forwards or ETFs, can mitigate risks associated with adverse exchange rate shifts
Strategic advice: Diversify not only by asset class but also by currency to spread risk and enhance long-term portfolio resilience.
Remittances and Money Transfers
Migrant workers sending money home rely on efficient, low-cost currency transfer methods. Remittances are a lifeline for many families, making exchange rates and transfer fees critically important.
- Traditional wire services often charge high fees and offer poor exchange rates, reducing the final amount received
- Digital platforms like Wise, Revolut, or PayPal typically offer lower fees and mid-market exchange rates
- Some countries impose limits or taxes on incoming remittances, affecting net value
Critical factor: Always compare total cost (fees + exchange rate margin), not just headline fees, to ensure maximum value reaches the recipient.
Online Shopping and E-Commerce
With the rise of global marketplaces like Amazon, Alibaba, and Etsy, consumers regularly purchase goods priced in foreign currencies. Understanding currency conversion ensures fair pricing and avoids unexpected charges.
- Merchants may display prices in your local currency using dynamic pricing, which can include a markup of 3–5%
- Payment processors like Visa or Mastercard apply their own exchange rate when settling transactions
- Import duties and VAT may be added at checkout or upon delivery, separate from the listed price
Smart shopper tip: Use a multi-currency card or check the final charge in your bank statement to verify actual conversion rates applied.
Currency in the Digital Age
Beyond traditional uses, digital currencies and fintech innovations are reshaping how we interact with money. From stablecoins pegged to the USD to central bank digital currencies (CBDCs), the future of currency is evolving rapidly.
- Mobile payment platforms integrate real-time currency conversion for cross-border transactions
- Cryptocurrencies offer alternative value transfer mechanisms, though with higher volatility
- Fintech apps now provide instant currency comparisons, budgeting tools, and automated hedging for travelers and investors
Emerging trend: Financial literacy now includes understanding digital currency ecosystems and their impact on traditional monetary systems.
Expert Insight: Whether you're a traveler, investor, or online shopper, staying informed about currency movements and using trusted financial tools can significantly improve your financial outcomes. Always verify exchange rates through independent sources like central bank data or financial news platforms, and avoid making large transactions during periods of high volatility unless properly hedged.
| Scenario | Key Currency Factor | Recommended Tool or Strategy | Potential Risk if Ignored |
|---|---|---|---|
| Daily Transactions | Purchasing power and inflation | Budgeting apps with real-time expense tracking | Reduced standard of living due to rising costs |
| Travel & Exchange | Exchange rate spreads and fees | No-fee travel cards or multi-currency wallets | Loss of 5–15% on converted funds |
| Investments | Currency volatility and hedging | Forex hedged ETFs or forward contracts | Eroded returns despite strong asset performance |
| Remittances | Transfer fees and exchange margins | Digital remittance platforms (e.g., Wise, Remitly) | Unnecessary loss of income for recipients |
| E-Commerce | Dynamic pricing and DCC markups | Price comparison tools and currency converters | Overpaying due to hidden conversion costs |
Additional Considerations
- Financial Inclusion: Access to fair currency exchange services can empower underserved populations, especially in remittance-dependent economies
- Regulatory Compliance: Cross-border transactions must adhere to anti-money laundering (AML) and know-your-customer (KYC) regulations
- Environmental Impact: Digital transactions reduce the need for physical currency production and transportation, lowering carbon footprint
- Psychological Effects: Currency devaluation can lead to loss of consumer confidence and economic uncertainty
- Future Trends: AI-driven currency forecasting and blockchain-based settlements are set to revolutionize how we manage money globally
How to Choose the Right Currency for Investment and Transactions
Effectively managing money in a global economy requires more than just basic financial literacy—it demands a strategic understanding of currency exchange dynamics, fee structures, and risk mitigation. Whether you're investing internationally, purchasing goods from overseas, or planning travel, selecting the right currency and exchange method can significantly impact your financial outcomes. This guide provides actionable insights to help you navigate currency decisions with confidence, minimize exchange costs, and optimize returns.
Important Note: Currency values fluctuate constantly due to economic indicators, geopolitical events, and market sentiment. Always assess your risk tolerance and consult a financial advisor before making significant currency-based investments.
Key Strategies for Smart Currency Management
- Stay Informed on Exchange Rates
Exchange rates are dynamic and influenced by central bank policies, inflation, interest rates, and global trade balances. Even minor fluctuations can have a substantial impact on your purchasing power or investment value—especially when dealing with large sums or frequent transactions.
- Use real-time financial platforms like Bloomberg, Reuters, or XE to monitor live currency rates
- Follow central bank announcements and economic calendars to anticipate rate shifts
- Track historical trends to identify patterns and potential reversal points
- For international investors, consider setting up rate tracking dashboards for key currencies (e.g., USD, EUR, JPY, GBP)
- Compare Exchange Services Thoroughly
Not all currency exchange providers offer the same value. Banks, airport kiosks, online platforms, and peer-to-peer services often have vastly different rates and fee structures. A seemingly competitive rate may be offset by hidden charges.
- Compare the mid-market rate (true exchange rate) versus the rate offered by providers
- Check both online and physical exchange outlets—online services often offer better rates
- Use comparison tools like CompareRemit or Monito to evaluate total transaction costs
- Avoid exchanging currency at airports or hotels, where margins are typically highest
- Understand All Fees and Commissions
Many currency services generate profit through hidden fees rather than transparent pricing. These can include service charges, transfer fees, spread markups, and account maintenance costs.
- Look for providers that disclose the total cost upfront, including any spread above the mid-market rate
- Beware of "zero-fee" claims—these often mask the cost in an inflated exchange rate
- Ask about receiving currency in cash vs. digital form, as processing fees may differ
- For business transactions, consider using multi-currency accounts to reduce recurring exchange costs
- Utilize Online Tools and Automation
Leveraging technology can streamline currency management and improve timing. Automated tools help you act quickly when favorable rates appear, reducing emotional decision-making.
- Use currency converters with historical data to analyze rate trends
- Set up rate alerts via apps like OANDA or Google Finance to notify you when a target rate is reached
- Employ limit orders on forex platforms to automatically exchange at your desired rate
- Explore digital wallets (e.g., Wise, Revolut) that offer real-time exchanges and multi-currency holdings
- Diversify Currency Holdings Strategically
Just as stock portfolio diversification reduces risk, holding multiple currencies can protect against volatility in any single economy. This is especially valuable for international investors, expatriates, and global businesses.
- Balance holdings between stable currencies (e.g., USD, EUR, CHF) and high-growth potential currencies (e.g., emerging market currencies)
- Consider geopolitical stability, inflation rates, and monetary policy when selecting currencies
- Rebalance your currency portfolio periodically based on economic outlooks
- Use currency ETFs or forex accounts for diversified exposure without direct cash handling
| Strategy | Best For | Time Commitment | Recommended Tools |
|---|---|---|---|
| Real-Time Rate Monitoring | Frequent traders, international investors | High (daily tracking) | XE, Bloomberg, Forex apps |
| Service Comparison | One-time large transfers, travelers | Medium (research phase) | Monito, CompareRemit, bank rate sheets |
| Fees & Commissions Analysis | Businesses, regular remitters | Medium (setup + review) | Wise, PayPal, banking statements |
| Online Automation Tools | Tech-savvy users, passive investors | Low (after setup) | OANDA, Google Finance, Revolut |
| Currency Diversification | Long-term investors, global earners | Low (periodic rebalancing) | Multi-currency accounts, ETFs, forex brokers |
Expert Tip: Consider using a multi-currency account if you frequently engage in international transactions. These accounts allow you to hold, exchange, and transfer money in multiple currencies at competitive rates, reducing reliance on traditional banks and minimizing conversion fees over time.
Additional Best Practices
- Plan Ahead: Avoid last-minute exchanges, which often result in poor rates due to urgency
- Lock in Rates: Use forward contracts for large future payments to hedge against adverse movements
- Monitor Economic Indicators: Track GDP, inflation, and interest rate decisions in target countries
- Keep Records: Document all currency transactions for tax, accounting, and performance tracking
- Stay Secure: Only use regulated and licensed exchange providers to avoid fraud
Choosing the right currency and exchange strategy is a powerful way to enhance financial efficiency and protect your wealth in an interconnected global economy. By staying informed, comparing options, leveraging technology, and diversifying wisely, you can minimize costs and maximize the value of your money across borders. For complex or high-value transactions, consider consulting a certified financial planner or foreign exchange specialist to ensure optimal decision-making.
Frequently Asked Questions About Currency Exchange and Travel Finance
Q1: How is the money shop currency rate important to international travelers?Understanding the currency exchange rate at places like The Money Shop is crucial for any international traveler aiming to make the most of their trip—both financially and experientially. Exchange rates determine how much local currency you receive for your home currency, directly impacting your purchasing power abroad.
- Budget Planning: Knowing the current rate helps travelers estimate daily expenses for meals, transportation, attractions, and accommodations, enabling them to set realistic spending limits.
- Avoiding Overpayment: Unfavorable rates or poor timing can result in significant losses. Comparing rates across providers ensures you're not losing money unnecessarily.
- Maximizing Value: A favorable exchange rate means more spending power, allowing travelers to enjoy premium experiences or extend their stay without exceeding their budget.
- Emergency Preparedness: Awareness of fluctuating rates helps travelers anticipate potential cost increases due to market changes during long trips.
Smart travelers often monitor rates before departure and use apps or online tools to find the best available options at airports, banks, or specialized exchange services like The Money Shop.
Q2: Are there any fees associated with currency exchange at The Money Shop?Yes, while The Money Shop provides convenient access to foreign currencies, it’s important to be aware that exchange services often include fees or hidden costs that can reduce the overall value of your transaction.
- Commission Fees: Some locations charge a direct commission on the amount exchanged, which may not always be clearly disclosed.
- Markup on Exchange Rates: Instead of charging a visible fee, many providers—including retail exchange outlets—build a margin into the displayed rate, offering less favorable terms than the mid-market rate.
- Service Charges: Additional handling or service fees may apply, especially for small transactions or less common currencies.
- No-Fee Claims: Be cautious of “no fee” promotions—these often compensate by offering worse exchange rates.
To minimize costs, compare The Money Shop’s total effective rate (including all fees) with online providers, banks, or credit card companies. Using a no-foreign-transaction-fee card for purchases and withdrawing cash from ATMs abroad can sometimes offer better value than upfront currency exchange.
Q3: How frequently do currency rates fluctuate?Currency exchange rates are highly dynamic and can change multiple times per day due to the continuous operation of global financial markets. These fluctuations are driven by a complex interplay of economic, political, and social factors.
- Real-Time Changes: Rates update constantly during market hours, influenced by trading activity in major financial centers like London, New York, and Tokyo.
- Economic Indicators: Data such as inflation rates, interest rate decisions, employment figures, and GDP growth directly impact currency strength.
- Political Events: Elections, geopolitical tensions, or policy changes can cause sudden volatility in exchange rates.
- Market Sentiment: Investor confidence, speculation, and risk appetite also influence currency valuations.
For international travelers, investors, or online shoppers, staying informed about these movements is essential. Monitoring trusted financial news sources or using real-time currency converter apps can help identify optimal times to exchange money. Those exchanging large amounts may consider setting rate alerts or using forward contracts to lock in favorable rates.
Q4: What are some common security tips for handling currency?Safeguarding your money—both physical cash and digital funds—is a critical aspect of safe and stress-free travel. Whether you're exchanging currency at The Money Shop or using money abroad, follow these best practices to protect against theft and fraud.
- Secure Cash Storage: Use anti-theft travel wallets, money belts, or hidden pouches to store cash discreetly and reduce the risk of pickpocketing in crowded areas.
- Diversify Holdings: Split your cash and cards between different locations (e.g., hotel safe, carry-on bag, wallet) so that losing one doesn’t leave you stranded.
- Monitor Bank Activity: Regularly check your bank and credit card statements for unauthorized transactions. Enable mobile alerts for all account activity.
- Use Two-Factor Authentication (2FA): Secure all digital financial accounts with 2FA to prevent unauthorized access, especially when using public Wi-Fi.
- Protect Personal Information: Never share PINs, passwords, or personal identification details. Shred or securely store receipts containing sensitive data.
- Avoid Counterfeit Risk: Inspect bills for watermarks, security threads, and color-shifting ink when receiving change, especially in high-risk regions.
By combining physical precautions with digital security habits, travelers can significantly reduce financial risks while abroad.
Q5: Can digital currencies impact traditional currency systems?Yes, digital currencies—especially cryptocurrencies like Bitcoin and Ethereum—are increasingly influencing traditional financial systems and central banking models around the world.
- Increased Competition: Cryptocurrencies offer faster, borderless, and often cheaper cross-border transactions compared to traditional banking systems, pushing banks and payment processors to improve speed and reduce fees.
- Innovation in Security: Blockchain technology has prompted financial institutions to adopt stronger encryption, decentralized ledgers, and enhanced fraud detection mechanisms.
- Central Bank Digital Currencies (CBDCs): In response to crypto adoption, many governments are developing their own digital currencies (e.g., China’s digital yuan, the ECB’s digital euro) to maintain control over monetary policy and financial stability.
- Financial Inclusion: Digital currencies can provide banking access to unbanked populations, challenging traditional banking monopolies and encouraging more inclusive financial services.
- Regulatory Challenges: The rise of crypto has led to new regulations aimed at preventing money laundering, tax evasion, and consumer protection issues.
While traditional currencies remain dominant, the growing presence of digital alternatives is driving innovation, transparency, and efficiency across the global financial landscape. Travelers may soon see more options for using digital wallets or stablecoins for international payments, further transforming how we think about money exchange.