Your credit report is one of the most important financial documents you’ll ever access. It influences your ability to secure loans, rent an apartment, or even land certain jobs. Among the three major credit bureaus—Experian, Equifax, and TransUnion—Experian holds detailed records on millions of consumers. Knowing how to unlock your Experian credit report correctly ensures you get accurate information while protecting your identity from fraud.
Thanks to federal law, you’re entitled to a free credit report from each bureau every 12 months. The process should be secure, straightforward, and transparent. Yet many people encounter confusion, hidden fees, or misleading websites promising “instant” access. This guide walks you through the legitimate, safe method to unlock your Experian report—no subscriptions, no traps.
Why Your Experian Credit Report Matters
Experian compiles data from lenders, banks, and creditors to create a comprehensive picture of your financial behavior. This includes payment history, outstanding balances, credit utilization, public records (like bankruptcies), and recent inquiries. Lenders use this information to assess risk when you apply for credit cards, auto loans, or mortgages.
Regularly reviewing your Experian report helps you:
- Detect errors that could hurt your score
- Spot signs of identity theft early
- Understand what factors are influencing your creditworthiness
- Prepare for major financial decisions with confidence
“Monitoring your credit isn’t just about knowing your score—it’s about catching inaccuracies before they derail your goals.” — Sarah Lin, Consumer Financial Advocate
Step-by-Step: How to Access Your Experian Report Safely
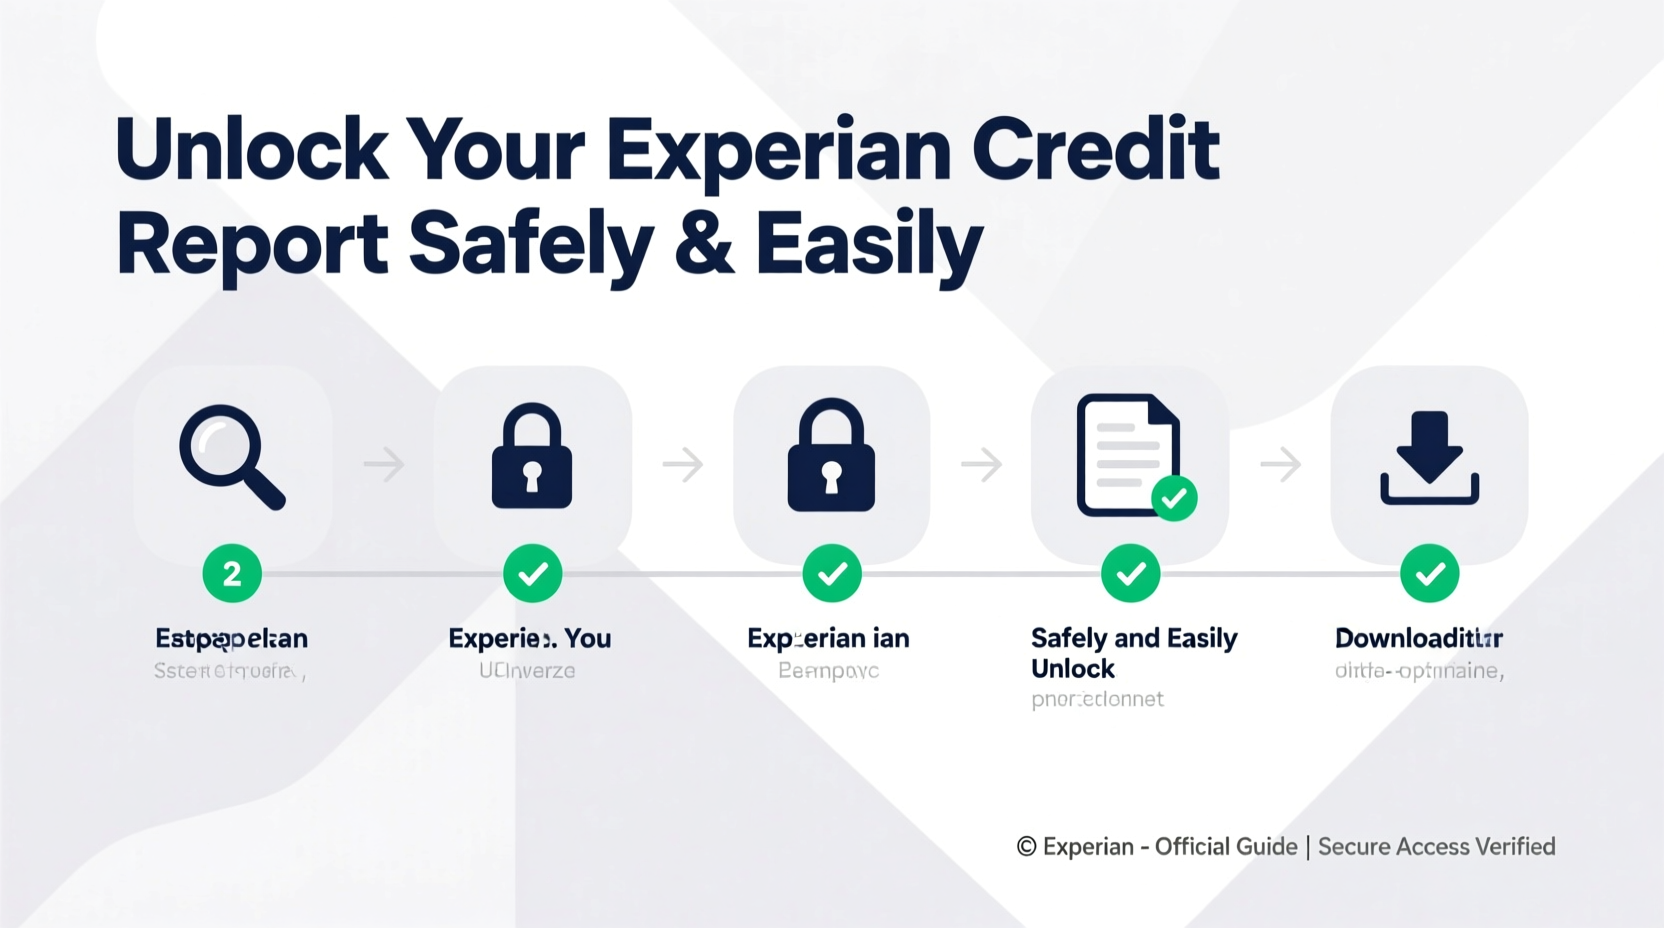
The safest way to unlock your Experian credit report is through AnnualCreditReport.com, the only government-authorized website for free credit reports. Third-party sites may offer similar services but often bundle them with paid monitoring plans. Follow these steps carefully to avoid unnecessary charges.
- Visit AnnualCreditReport.com
Do not search for “free Experian report” in Google—this can lead to lookalike sites. Type the URL directly into your browser to ensure authenticity. - Select Experian as Your Bureau
On the site, choose Experian from the list of credit reporting agencies. You can request reports from all three bureaus at once or stagger them throughout the year for ongoing monitoring. - Provide Required Personal Information
You’ll need to enter your full name, Social Security number, date of birth, and current address. If you’ve lived elsewhere in the past two years, you may need to verify those addresses too. - Answer Security Verification Questions
Experian will present real-time questions based on your credit history—such as “Which of these accounts do you own?” or “What was the balance on your car loan in 2021?” These confirm your identity without requiring passwords. - View and Download Your Report
Once verified, you can view your full Experian credit report instantly. Save it as a PDF for future reference.
What to Do After Unlocking Your Report
Now that you have your Experian report, don’t just file it away. Use it actively to manage your financial health.
Review for Accuracy
Check every account listed. Confirm dates, balances, and statuses. Look out for:
- Accounts you didn’t open
- Payments marked late that were actually on time
- Closed accounts reported as open
- Duplicate collections or outdated negative entries (older than seven years)
Dispute Errors Immediately
If you find inaccuracies, dispute them directly through Experian’s online dispute center. Provide documentation such as payment receipts or account statements. By law, Experian must investigate within 30 days.
Monitor for Fraud Indicators
Fraudulent activity often appears as unfamiliar hard inquiries, new accounts, or address changes you didn’t make. If detected, place a fraud alert or freeze your credit immediately via Experian’s security tools.
Common Mistakes to Avoid
| Mistake | Why It’s Risky | How to Avoid |
|---|---|---|
| Using unofficial third-party sites | Many charge hidden fees or enroll you in trials that convert to paid plans | Only use AnnualCreditReport.com for free reports |
| Sharing SSN over unsecured connections | Increases exposure to phishing and data theft | Always check for HTTPS and avoid mobile hotspots |
| Not verifying answers before submitting | Failed verification delays access and may trigger flags | Have utility bills or bank statements handy for reference |
| Ignoring the report after download | Missed errors can affect credit decisions later | Schedule annual reviews—or better, quarterly checks |
Real Example: Recovering From Identity Theft
Jamie R., a teacher from Austin, TX, accessed her Experian report ahead of buying her first home. She discovered a $4,500 personal loan under her name—one she never applied for. The account was opened six months earlier, and payments were delinquent.
She filed a dispute online, uploaded her ID and proof of address, and requested a fraud alert. Within 10 days, Experian removed the fraudulent account. Her FICO score jumped 72 points, allowing her to qualify for a lower mortgage rate.
This case highlights why proactive monitoring matters. Without checking her report, Jamie might have faced denial—or worse, spent years repaying someone else’s debt.
Tip: Stagger your free reports—pull one every four months (e.g., Experian in January, Equifax in May, TransUnion in September) for year-round insight.Frequently Asked Questions
Will checking my Experian report hurt my credit score?
No. When you request your own report, it’s considered a soft inquiry, which does not impact your credit score. Only hard inquiries from lenders can affect it.
Can I get my Experian report if I’ve been denied credit?
Yes—and you should. Federal law allows you to request a free report within 60 days of any adverse action, such as a loan denial. Use Experian’s official dispute page or call their dedicated line for assistance.
Is Experian’s free FICO score included with the report?
Not through AnnualCreditReport.com. However, Experian offers a free tier on its own website that includes your FICO Score 8 based on Experian data. Enrolling requires identity verification but no credit card.
Final Checklist: Unlocking Your Experian Report
- ✅ Visit AnnualCreditReport.com directly
- ✅ Select Experian as your bureau
- ✅ Gather personal details: SSN, DOB, addresses
- ✅ Prepare to answer dynamic verification questions
- ✅ Review report thoroughly upon access
- ✅ Dispute errors immediately if found
- ✅ Save a secure copy and store offline
Take Control of Your Financial Future
Accessing your Experian credit report isn't just a formality—it's a powerful act of financial self-care. With the right approach, you can uncover hidden issues, correct mistakes, and build stronger credit over time. The process takes less than 15 minutes, yet the benefits last for years.
Don’t wait for a loan application to reveal surprises. Take action now. Unlock your Experian report the safe, legal way, and arm yourself with knowledge that empowers smarter decisions.
💬 Did you find something unexpected on your report? Share your experience below—your story could help others avoid the same pitfalls.