Credit inquiries are a standard part of the lending process, but not all inquiries are created equal. When you apply for credit—whether it’s a credit card, auto loan, or mortgage—a lender typically checks your credit report. This action is recorded as a credit inquiry, and depending on the type, it can influence your credit score. Understanding the mechanics behind these inquiries and their consequences empowers you to make informed financial decisions without unintentionally harming your creditworthiness.
What Are Credit Inquiries?
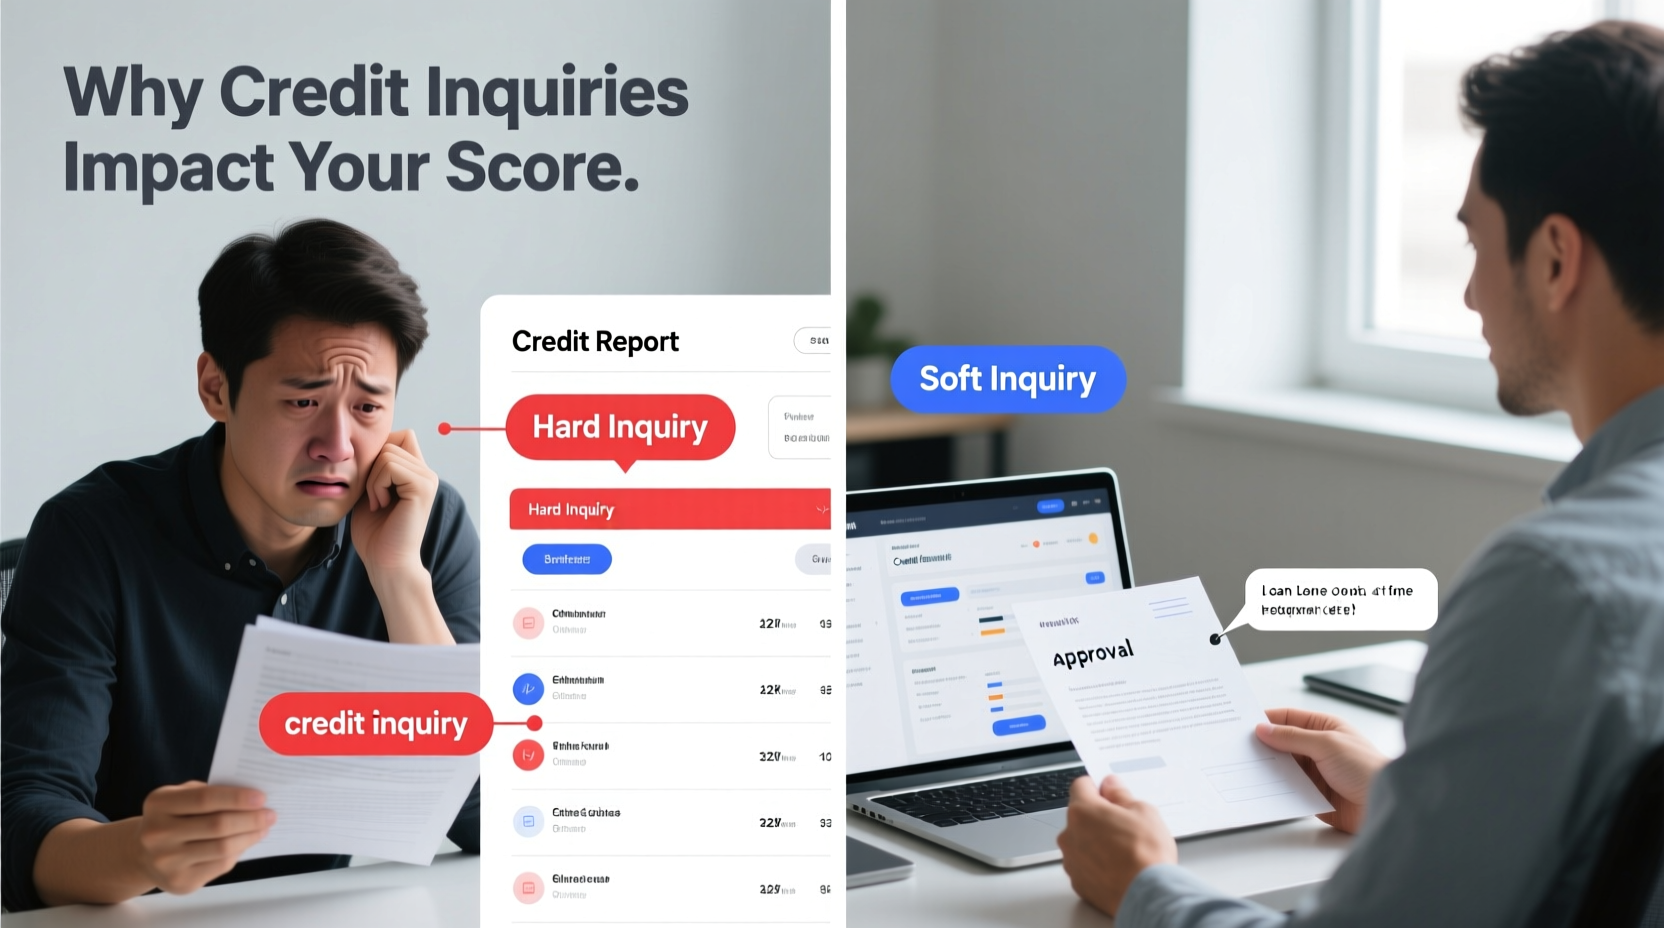
A credit inquiry, also known as a credit check, occurs when a lender or creditor accesses your credit report to evaluate your financial reliability. These inquiries are logged by the three major credit bureaus: Equifax, Experian, and TransUnion. They fall into two main categories: hard inquiries and soft inquiries.
Hard inquiries happen when a financial institution checks your credit report with your permission as part of a lending decision. Examples include applying for a new credit card, car loan, or mortgage. These are visible to lenders and can affect your credit score.
Soft inquiries, on the other hand, do not impact your credit score. They occur when you check your own credit, when an employer runs a background check (with consent), or when a company pre-approves you for an offer. Soft inquiries are only visible to you and do not signal new credit applications to lenders.
Tip: Checking your own credit through services like AnnualCreditReport.com or credit monitoring apps results in a soft inquiry—completely safe for your score.Why Hard Inquiries Affect Your Credit Score
Hard inquiries are factored into your FICO and VantageScore models because they can indicate financial behavior that may increase lending risk. Statistically, individuals who open several credit accounts in a short period are more likely to become overextended and default on payments. As a result, each hard inquiry typically causes a small, temporary dip in your credit score—usually less than five points per inquiry.
The effect is generally short-lived. Most hard inquiries remain on your credit report for two years but only influence your FICO score for 12 months. Over time, as you maintain responsible credit habits—like paying bills on time and keeping balances low—the impact fades.
“Multiple hard inquiries in a short timeframe can signal higher risk to lenders, even if the actual drop in score is minimal.” — John Carter, Consumer Credit Advisor at Fair Isaac Corporation
Rate Shopping and Multiple Inquiries
One common concern is whether shopping around for the best interest rate will hurt your credit. The good news is that credit scoring models account for rate shopping. When you're comparing loan offers for a mortgage, auto loan, or student loan, multiple inquiries within a specific window—typically 14 to 45 days—are treated as a single inquiry.
This grace period allows you to seek competitive rates without being penalized repeatedly. However, this rule primarily applies to installment loans. For credit cards, each application usually counts as a separate hard inquiry, so it's wise to be selective.
| Inquiry Type | Impact on Credit Score | Duration on Report | Lender Visibility |
|---|---|---|---|
| Hard Inquiry | Minor negative impact (5–10 pts max) | 2 years | Visible to all lenders |
| Soft Inquiry | No impact | Not reported to others | Only visible to you |
How to Minimize the Impact of Credit Inquiries
You don’t need to avoid credit altogether, but managing how and when you allow hard inquiries can protect your credit health. Here’s a practical step-by-step guide:
- Check your credit report regularly using free services. This ensures you catch errors early and monitor existing inquiries.
- Pre-qualify when possible. Many lenders offer pre-qualification tools that use soft inquiries to estimate approval odds.
- Consolidate applications. If you’re rate shopping, complete all applications within a 14–45 day window to benefit from inquiry clustering.
- Avoid unnecessary credit applications. Each new card or loan adds a hard inquiry—even if you’re approved, the cost to your score may outweigh the benefit.
- Space out credit requests. Waiting at least six months between non-essential applications gives your score time to recover.
Mini Case Study: Sarah’s Auto Loan Search
Sarah needed a new car and planned to finance it. She researched lenders and contacted four different banks over a 10-day period to compare rates. Each bank performed a hard inquiry, resulting in four entries on her credit report. However, because all inquiries were for an auto loan and occurred within a short timeframe, FICO treated them as a single event. Her score dropped by just three points temporarily and rebounded within two months after she made timely payments on the new loan. By contrast, had she applied for two credit cards during the same period, those would have counted as separate inquiries and caused a larger cumulative impact.
Actionable Checklist: Managing Credit Inquiries Wisely
- ✅ Review your credit report quarterly for unauthorized hard inquiries.
- ✅ Use pre-qualification tools to avoid surprise hard pulls.
- ✅ Limit new credit applications unless necessary.
- ✅ Complete all loan comparisons within a 30-day window.
- ✅ Dispute any unfamiliar hard inquiries directly with the credit bureaus.
- ✅ Monitor your score trends after applying for credit.
Frequently Asked Questions
Do soft inquiries affect my credit score?
No. Soft inquiries have no impact on your credit score. They are used for background checks, personal reviews, or promotional offers and are not visible to lenders.
Can I remove a hard inquiry from my credit report?
You can dispute inaccurate or fraudulent hard inquiries with the credit bureau. Legitimate inquiries cannot be removed early but will expire after two years.
How many points does a hard inquiry lower my score?
Typically, one hard inquiry lowers your FICO score by fewer than five points. The exact amount depends on your overall credit profile—those with limited credit history may see a slightly larger impact.
Conclusion: Take Control of Your Credit Health
Credit inquiries are a natural part of borrowing, but understanding their role helps you navigate the system with confidence. Hard inquiries carry minor, short-term effects, while soft inquiries pose no risk. By planning applications strategically, using pre-approval tools, and staying informed through regular credit monitoring, you can minimize unnecessary impacts and maintain strong credit standing.
💬 Ready to take charge of your credit? Pull your free credit report today, review your inquiry history, and start making smarter borrowing decisions. Share this guide with someone who’s shopping for credit—it could save their score.